
Part 2 of 3 — A Season of Check-Ins
By Mark Zembo, Wealth Management Advisor
Elevage Partners | October 7, 2026
This past summer, my family tried something new: back-to-back reunions over the course of 10 days. We spent a few days with family in northern Ohio, then got back in the car and headed straight to a second reunion in the Outer Banks of North Carolina.
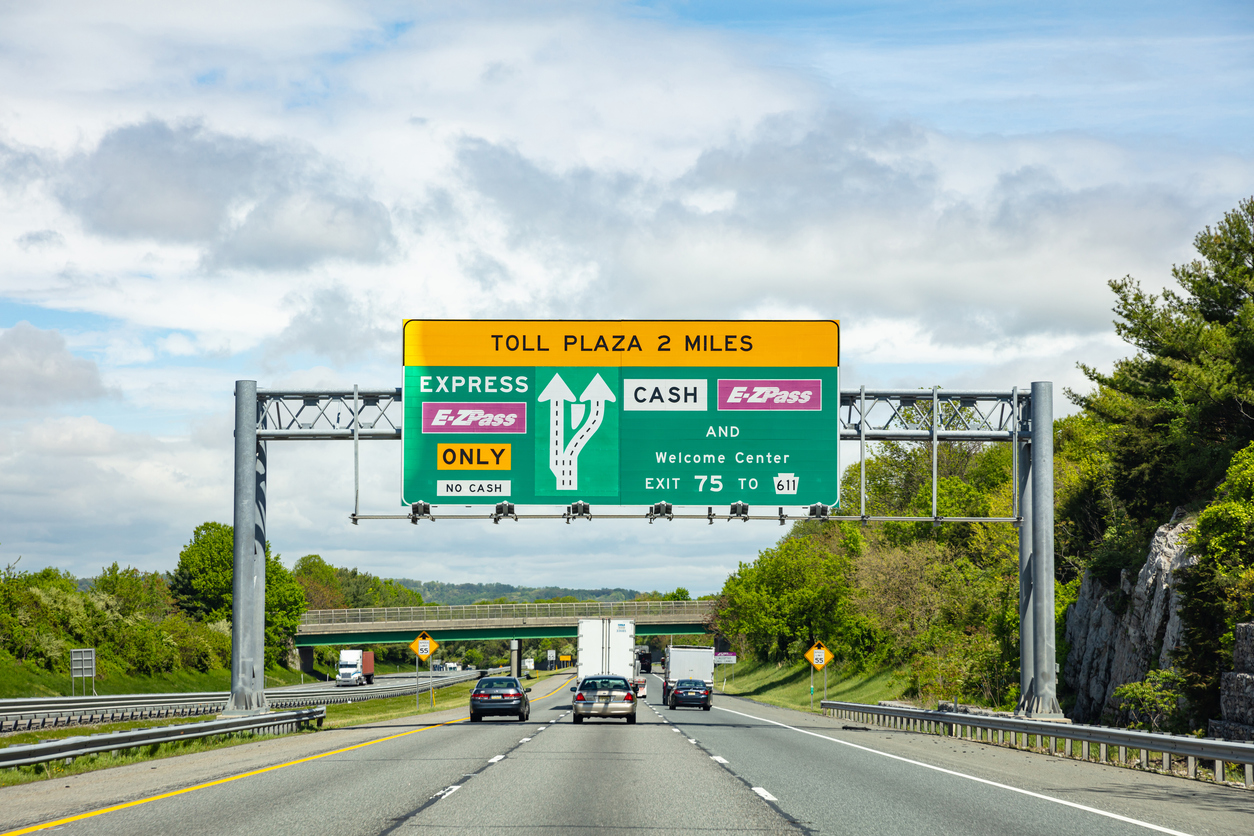
Along the way, our navigation app offered a faster route on a highway none of us had driven before. We took it. We had a big family birthday party waiting for us at the end of the drive, so saving a little time felt like an easy choice.
A few weeks later, a bill arrived with a photo of my license plate, the toll we owed and a penalty notice for not paying on time. Nothing had stopped us from using the road. The obligation was there all along; we simply hadn’t planned for it.
Required minimum distributions can work a little like that, too. Part 2 of this check-in series is about this stretch of the financial journey. For anyone who turned 73 this year or is soon celebrating this age, or who is already past it, the toll on tax-deferred retirement savings is coming due … but without the reminder notice in the mail. You are simply expected to know it.
For decades, traditional IRAs, 401(k)s and similar accounts have allowed retirement savings to grow without an annual tax bill. Tax deferral allowed more of the money to remain invested and continue compounding along the way. But the road was never tax-free. RMD rules generally begin at age 73, requiring a minimum amount to come out of tax-deferred retirement accounts each year. Those distributions are generally taxed as ordinary income.¹
Your first RMD is for the year you turn 73, although you generally have until April 1 of the following year to take it. After that, RMDs are due by Dec. 31 each year.¹ Miss one, or take too little, and the IRS may charge a 25% excise tax on the amount you should have withdrawn. The tax can drop to 10% if the shortfall is corrected within the applicable correction window,¹ and in some cases the IRS may waive the tax when the shortfall resulted from a reasonable error and steps are being taken to correct it.² An overlooked deadline, however, can turn an ordinary distribution requirement into an unnecessarily expensive mistake.
A few details can catch people off guard. Waiting until April 1 to take your first RMD means you will also have another RMD due by Dec. 31 of that same year, potentially putting two taxable distributions into one calendar year. If you’re still working, your employer’s plan may allow you to delay RMDs from that plan until retirement, unless you’re a 5% owner of the business sponsoring the plan. That exception does not apply to traditional IRAs.¹ Roth IRAs and designated Roth accounts in 401(k) and 403(b) plans do not require distributions while the original owner is alive.¹ That’s one reason the Roth-or-traditional question from the first post in this series matters long before 73.
As with many financial considerations, the RMD itself isn’t the problem. The problem is being surprised by it. Knowing the requirement is coming gives you time to consider when during the year to take the distribution, how much tax to withhold, whether to direct part of it to a charity you care about through a qualified charitable distribution,³ and how the additional income may interact with Social Security and Medicare premiums. Those are decisions to talk through with your tax advisor now, in early fall. Waiting until the final days of the year to lock in a strategy may not give you enough time to execute it.
On our drive, the time we saved went to the people at the end of the road. We made it in time for one big party celebrating every summer birthday in the family. That’s the part worth planning for. An RMD is one line on a tax form. What it pays for is the trip you saved for in the first place: time with family, a gift to a cause you believe in, a little more room to enjoy the years you worked for.
If you or someone you love is approaching 73 and you’re not sure where the tolls are on your route, now is a good time to look at the map together. Write to us at info@elevagepartners.com.
Sources
1. Internal Revenue Service, Retirement Topics – Required Minimum Distributions (RMDs), updated April 2026.
2. Internal Revenue Service, Instructions for Form 5329 (2025).
3. Internal Revenue Service, Retirement Plan and IRA Required Minimum Distributions FAQs.
This is a planning conversation, not tax advice. For the specific tax impact on your situation, please confirm with your tax advisor. Investing involves risk, including the possible loss of principal. Past performance does not guarantee future results. This reflects our current assessment and may change as conditions evolve.